A possession order does not evict anybody. It gives your landlord or lender permission to ask the court for the thing that does: a warrant.
So the eviction is real. It is also not happening tomorrow, and it can often be stopped.
Your deadline is printed on the notice the bailiffs put through the door. And the court’s power to help you ends the moment the bailiffs hand the keys to the claimant.
One point of terminology first, because people confuse them all: ‘warrant for possession’, ‘warrant of possession’ and ‘warrant of eviction’ all mean the same county court instrument. The High Court version is called a writ of possession.
Why the warrant landed with no warning
A warrant is issued in one of two situations: you stayed past the date on an outright possession order, or you breached a suspended one, usually by missing a payment you agreed to make.
That second one catches people out. A suspended order made two years ago has not expired. It sits there quietly, and one missed instalment brings it back to life.
The claimant then applies for the warrant without notice to you, under CPR 83.26(2). No hearing. No warning letter. The first you hear about it is when the bailiffs’ notice lands on the mat.
One protection does hold throughout: only a county court bailiff can evict you on a warrant, or a High Court enforcement officer on a writ. Your landlord cannot change the locks and your lender cannot send someone round, whether you rent or have a mortgage.
Your real clock: the N54 and the next two to three weeks
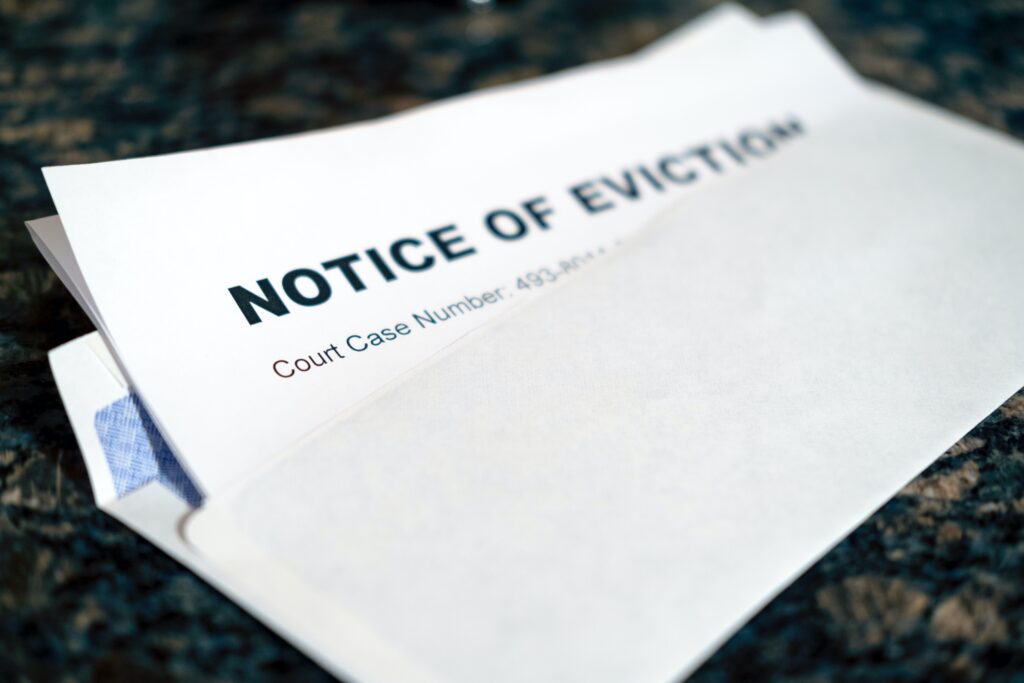
Bailiffs must deliver a Notice of Eviction (Form N54) to the property at least 14 days before the eviction date, either through the letterbox in a sealed transparent envelope or fixed up where you will see it. It gives the date and the time they will attend.
It also carries your claim number and your warrant number. Write both down now, because you need both to apply to stop it.
Fourteen days is the legal floor. What I see in practice sits right on top of it: when the letter from the court with a bailiff date arrives, it is normally no more than two to three weeks away from repossession.
You will see longer figures quoted, and they are measuring something different. Ministry of Justice figures for April to June 2026 put the median time from warrant to repossession at 10.1 weeks for mortgage cases and 9.4 weeks for landlord cases. That runs from the day the warrant was issued, which happened before anybody told you. Your clock starts with what the N54 says.
You are not being evicted this week. But you have a fortnight, not a season.
Eviction day, and the moment it becomes final
Bailiffs attend at the time on the notice, usually with the landlord or the lender’s agent. Everyone inside is asked to leave, including people who were never party to the case. Locks are changed and possession passes to the claimant.
Bailiffs can use reasonable force and bring a locksmith, but they cannot be violent or damage your belongings.
Once the warrant has been executed and the claimant has quiet possession, the court has no power to suspend it (Leicester CC v Aldwinkle).
Everything below works before that morning. Nothing works after it.
Route one: ask the landlord or lender to pull the warrant
The claimant can withdraw the warrant at any point before it is executed, which makes this the fastest and cheapest fix available. Paying the arrears in full, or fully putting right the breach that triggered the order, normally ends it there.
Homeowners have leverage tenants do not. Under the FCA’s mortgage rules (MCOB 13.3), your lender must consider your individual circumstances and must not repossess unless all other reasonable attempts to resolve the position have failed.
What a lender wants before it pauses anything is evidence rather than promises: the property on the market at a sensible price, the brochure and EPC, and permission to speak to your agent and conveyancer. Some lenders run Assisted Voluntary Sale schemes that hold court action and cover the selling fees while you sell.
If yours will not engage at all, the Financial Ombudsman Service takes complaints, although that on its own will not move the bailiff date.
Route two: apply to suspend the warrant on Form N244
If the claimant will not withdraw it, ask the court to suspend it. This costs far less and takes far less skill than most people facing eviction assume.
The fee is £16 to apply to suspend a warrant of possession (HMCTS EX50, as at 13 July 2026), and it is worth checking the current EX50 before you pay, because court fees move. On a low income or certain benefits, Help with Fees on Form EX160 removes it, and in an emergency the court can accept the remission application without the usual evidence.
- File at the right court: the county court hearing centre that made the possession order, not your nearest one.
- Say why on the form: why you fell behind, what has changed since, what you can pay now, and any exceptional hardship. A witness statement with a signed statement of truth is the cleanest way to put it.
- Attach the proof: a budget, wage slips or benefit award letters, a job start letter, medical evidence, receipts for payments already made.
- Mark it urgent and write the eviction date at the top. Hand it in at the counter if you can, then ring to confirm it arrived.
- Turn up to the hearing. Judges refuse applications when the applicant does not appear.
- Ring the bailiffs’ office yourself if you win. Do not assume the court’s message beats the bailiff’s van.
Applications are supposed to give at least 3 clear days’ notice (CPR 23.7), but the court can shorten that. You can apply right up to and including the morning of the eviction, and where no hearing can be listed in time, the court can grant a short stay while it finds you a slot. Shelter Legal sets out the process in detail.
Whether the court is even allowed to help you
Check this before you write a word, because it decides how much room the judge has.
Where the possession order was made on a discretionary ground, the power to suspend is broad, and a realistic offer backed by evidence is a genuine argument.
Where the ground was mandatory, the court can normally only postpone by up to 14 days, or six weeks for exceptional hardship (section 89 Housing Act 1980), and by warrant stage those weeks have usually been spent at the possession hearing already.
Which is which? Check the ground named on the order rather than working it out from the number. Broadly, the Part 1 grounds of Schedule 2 to the Housing Act 1988 are mandatory: numbers 1 to 8, plus the lettered grounds added alongside them, such as Ground 1A for selling. The Part 2 grounds, 9 to 17, are discretionary. The grounds and their notice periods changed on 1 May 2026. Orders made without a hearing, based on a section 21 notice served before that date, are the hardest of the lot to shift.
Wales: same forms, different tenancy law
The enforcement machinery is shared. Contract-holders in Wales get the same N54, the same 14 days and the same N244 application, and suspension still turns on whether the ground was discretionary. What differs is the underlying renting law, which sits in the Renting Homes (Wales) Act 2016. Mortgage repossession is not devolved in this respect.
Source: GOV.WALES
Route three, for homeowners: get to exchange before the bailiffs arrive
If there is equity in the house, you have an option a tenant does not. Sell it, and pay the lender off.
A court can suspend a warrant to let a sale complete, under section 36 of the Administration of Justice Act 1970. The evidence test comes from Bristol & West Building Society v Ellis: show the sale is likely, that the proceeds will clear the debt, and that the time you are asking for is reasonable. Shelter Legal confirms courts are more likely to allow time where a firm offer is already in place.
If a lender has already given you time to repay and the matter has been before a judge, the judge will not stop the bailiffs simply on an offer. An unaccepted offer, is a piece of paper saying that somebody might buy your house.
Exchange of contracts is what changes the whole conversation, because it is a binding sale with a fixed completion date.
That is exactly the evidence the Ellis test asks for.
In our experience, once contracts have been exchanged we prepare paperwork to make sure the repossession does not take place, which gives the seller time to find a new home while we proceed to completion. We help them relocate as well.
We have had many cases where somebody contacted us in the same week as their eviction date. We can make an offer that same day and, where it is needed, look to exchange contracts within 72 hours of the first phone call, with our panel solicitor then contacting the lender to confirm that contracts have exchanged.
Completion normally follows in two to four weeks, averaging 28 days. Our fastest ever was seven days, on a repossession.
One hard limit. Where the debt is bigger than the property is worth and there are no other funds, the court has no jurisdiction to suspend for a sale at all (Cheltenham & Gloucester v Krausz). In negative equity you need your lender’s agreement, not a judge’s.
Is a cash sale the wrong call? It depends on the stage
Shelter tells people to steer clear of quick sale companies and get proper valuations from local agents first. At first-letter stage that is good advice and I give it myself: a cash offer typically sits at 75% to 85% of open market value, and if you have months and no real pressure, that is a discount you do not need to take.
At bailiff stage the maths changes. There is no time to market the property with an agent, because a marketed sale takes up to 6 months to complete and you have a couple of weeks.
So the choice is no longer cash buyer against estate agent. It is a sale with a date you control against a repossession sale you have no say in.
Roughly half the homeowners who contact us about repossession already have a bailiff date. The other half act on the first letter or straight after the first court date, because they do not want to run up more court and solicitor fees. That second group nearly always ends up with more choices.
Free legal help you can get today
Advice and action are not alternatives. Start both this week.
The Housing Loss Prevention Advice Service (HLPAS) gives free legal advice on housing, debt and benefits plus representation in court on the day. It is not means tested, it covers homeowners as well as tenants, and all you need is written evidence that you are at risk of losing your home.
Also worth using: the duty adviser at the court, Civil Legal Advice, the “find a legal adviser” tool on GOV.UK, your council’s housing options team, and Shelter, Shelter Cymru or Citizens Advice.
Four things not to do in the next fortnight
- Do not hand the keys back without advice. Voluntary surrender feels tidier. It closes every route above and you still owe the money.
- Do not move out early. Leaving before you have to can get you treated as intentionally homeless, which can cost you the council’s duty to rehouse you.
- Do not assume a shortfall disappears. If the lender sells for less than you owe, the balance is still yours, and lenders generally have 12 years to pursue mortgage capital under the Limitation Act 1980.
- Do not spend the fortnight waiting to see if the money comes together. Every route here needs runway: the court prefers 3 clear days’ notice, and a sale needs solicitors instructed. A decent plan started on day two beats a perfect one started on day twelve.
Common questions
Can a possession order be set aside?
Sometimes, but the grounds are narrow: the warrant was issued too early, no notice of eviction was served, or the claimant misled the court. An appeal needs an error of law and is usually out of time by this stage. Applying to suspend the warrant is the realistic route for almost everyone holding an N54.
What if High Court enforcement officers turn up instead of county court bailiffs?
The claimant can transfer enforcement to the High Court, where an enforcement officer executes a writ of possession instead, which is usually quicker. They must still give at least 14 days’ notice, and you apply to stay or set aside the writ on the same Form N244 for the same £16 fee. Some mortgage lenders use them, so if enforcement agents write to you, get advice straight away.
Does breathing space stop a warrant?
While a breathing space or mental health crisis moratorium is in force, enforcement of the debts it covers must not progress, and that includes executing a warrant for rent arrears, even where the possession order was made on a mandatory ground. It is temporary and it does not clear the debt, so use the time to sort a longer-term answer.
Facing a Bailiff Date With Equity in Your Home?
We buy direct for cash, with no estate agents and no fees. Cash offer within 24 hours, exchange in as little as 48 hours where it is needed, and we cover your conveyancing when you use our recommended solicitor.
This article is general information about the law in England and Wales, not legal advice, and fees and rules change. For advice on your own case, speak to HLPAS, a court duty adviser, Shelter, Shelter Cymru or Citizens Advice. Property Rescue is regulated by the FCA for Sale and Rent Back only (FCA Register 522471).